Pension consolidation: The golden opportunity for employers hiding in plain sight
A Google search will quickly yield reams of content about the benefits of individuals bringing their pensions together, how and why they should do it, etc. But while much of this is useful and necessary, there’s usually a key stakeholder missing from the conversation – the employer.
Now, you may not think so at first, but employers can stand to gain a lot from encouraging employees to combine their pensions into their workplace pension scheme. In fact, I’d go as far as to say that it’s one of the clearest opportunities employers have to unlock more value – without spending a penny extra.
Value and engagement go hand-in-hand
A workplace pension is typically one of the most expensive benefits an employer offers their employees. And most would agree it’s money well spent. For example, employees rank pension contributions as the second-most valuable workplace benefit after time off and flexibility, with almost three-quarters (74%) saying the quality of a pension scheme shows how much an employer cares about its people.
But here’s the question employers need to be asking: how much of their pension spend is actually landing as perceived value with their employees?
Engagement levels are the honest measure of that and the picture isn’t exactly encouraging. Our research found that 38% of employees have taken no action on their pension at all – no retirement target, no change to contributions, no beneficiaries added. One in ten has never even checked their balance.
So let’s be clear, a pension that employees don’t understand or engage with is a pension employers aren’t getting full value from – however much they’re contributing on their employees’ behalf. The flip side is just as true: improve engagement and you start to see better value from exactly the same spend.
This is where pension consolidation earns its place in the conversation. Of all the levers employers have to improve engagement, it’s one of the simplest, and one of the most overlooked.
Our Workplace Pension Report (2026) found that 35% of employees say they’d be more engaged with their pension if all their pots were in one place. Plus, among those who actually have pots elsewhere, 60% say they’d value their current pension more if consolidating was easy.
Overcoming the ‘new-starter’ problem
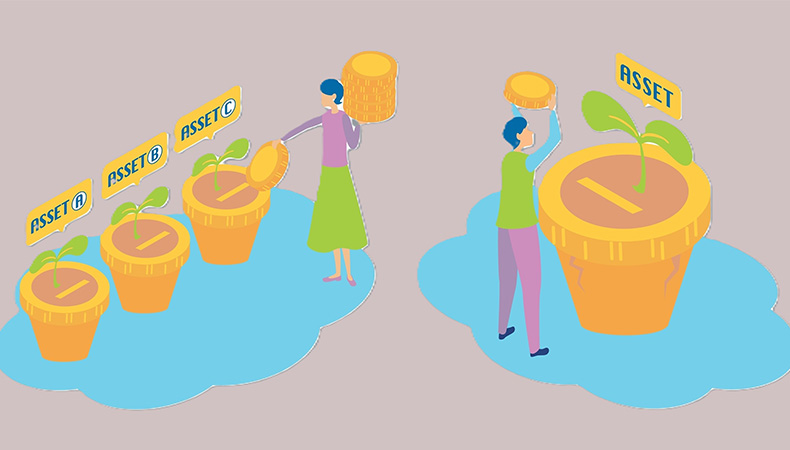
Why would something so simple make such a difference? Imagine you’re an employer onboarding a new starter. Day one, they have £0 in your pension scheme. Their real retirement savings – perhaps many years’ worth – are sitting with their previous provider (or, indeed, several others). For the first months, and even for many years, your scheme looks like the smallest pension pot they have.
It’s hard, then, for that new starter to fully value and appreciate the pension you’re paying into. All it takes, though, is to bring those old pots together into your scheme and they then see one meaningful balance, growing visibly, with your contributions clearly adding to it.
Make the process simple and you get a meaningful increase in perceived value – with no additional cost to the business.
The destination matters as much as the journey
Making the transfer process easy reduces friction for employees – but it’s only half the job. Think about how people switch banks or energy suppliers.
Nobody switches purely for the sake of it. They switch because the alternative is better – increased value, better service, or something that feels like an upgrade.
Pensions are no different. Employees won’t transfer years of savings into a scheme that doesn’t feel compelling – however smooth the journey is. The quality of the employer’s scheme and the ease of the process have to work together.
What good looks like
We’ve seen it work. When Donnelly Group, Northern Ireland’s largest family-owned car retailer, moved to Cushon, face-to-face sessions helped to build knowledge and confidence, and the app - took the effort out of transferring. The result: 34% of employees consolidated an old pension, more than double the 16% norm that we observed in our Workplace Pensions Report.
Donnelly didn’t spend any extra on the pension. They simply removed the barriers and made the case that the new scheme was worth moving to.
The power of accessibility
Ask your provider: can employees consolidate digitally, without jargon, and see their progress? Is there a human when they get stuck? Then ask the bigger question: is your scheme good enough that employees would want to bring their savings into it?
Get both of these right and the same pension spend works considerably harder – because your scheme stops being one small pot among many and becomes the only one that really matters.
Download the Employer Guide to Pension Consolidation here.
Supplied by REBA Associate Member, Cushon
Cushon is a workplace pensions and savings provider with an award-winning proposition.